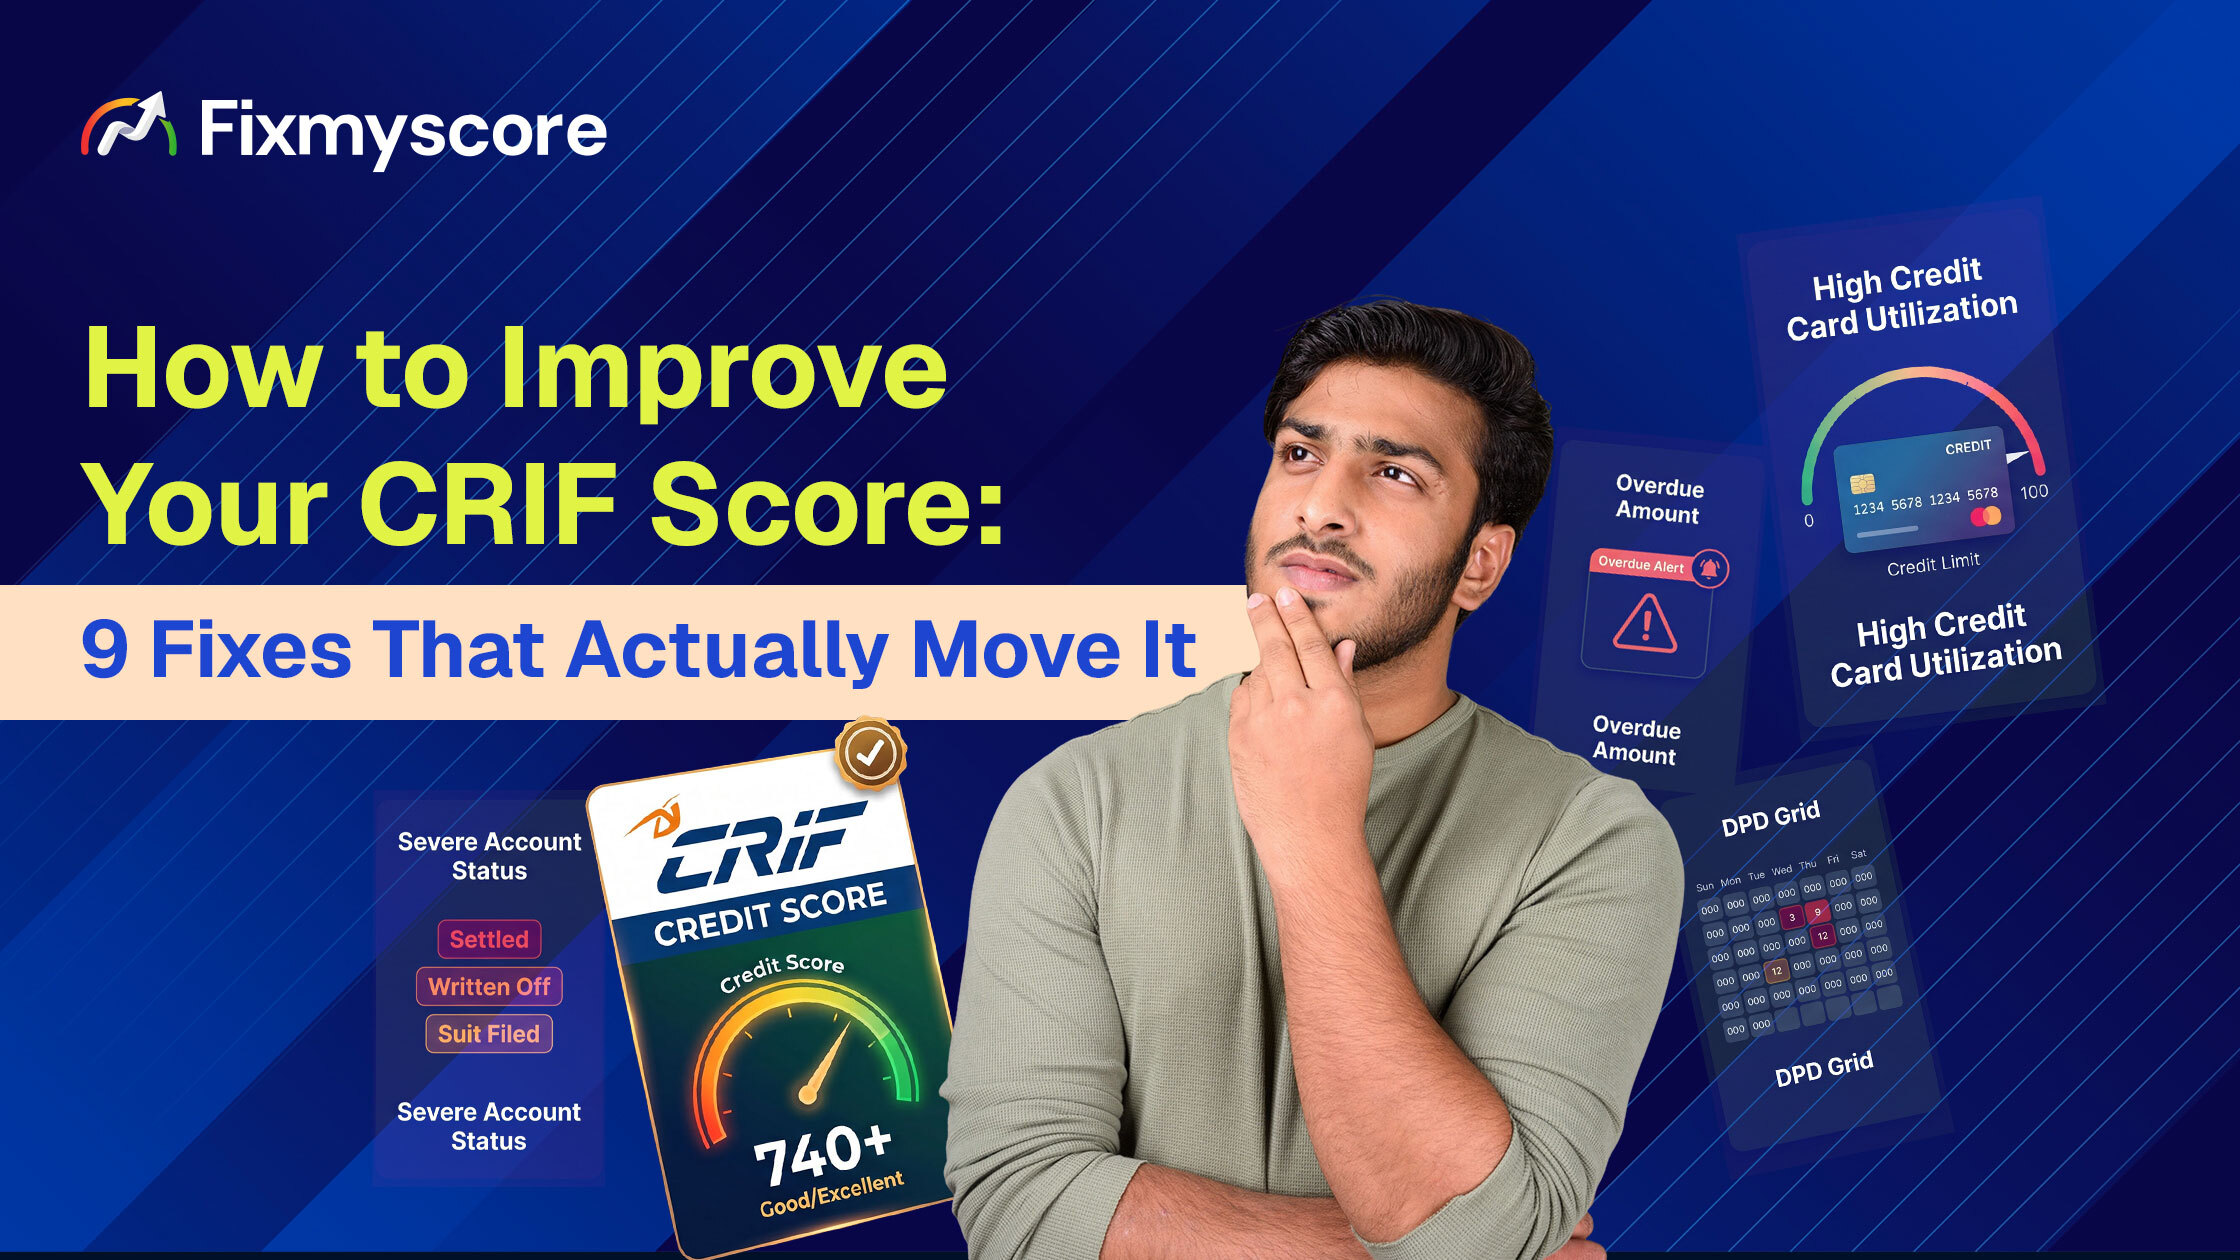
To improve your CRIF score, pay every EMI and card bill on time, keep your credit card balances under 30% of the limit, clear anything overdue, and get any errors on your report corrected. Most people see movement within one to three months, once their lenders have reported the changes to CRIF High Mark. Serious damage, like a written-off loan, takes longer, but it does fade.
Here's what to do, roughly in order of impact. If you're new to how the score works, our CRIF score guide explains the basics.
Start by reading your CRIF report
Advice is only useful once you know what's pulling your score down. Get your full CRIF report (you can check it free here) and look for these five things:
- Any account showing an overdue amount right now
- Late payments in the days past due (DPD) grid, where anything other than "000" means you paid late that month
- Credit cards where the balance is close to the limit
- Accounts marked "settled", "written off" or "suit filed"
- Loans you don't recognise, or closed loans still shown as active
It's also worth comparing your CRIF report with your CIBIL report. If the scores are far apart, our guide to CRIF vs CIBIL differences explains why.
Whatever you find decides which of the fixes below matter most for you.
9 ways to improve your CRIF score
1. Clear anything that's overdue, today
An account that's still overdue keeps getting worse every month it stays unpaid. Paying it doesn't erase the late months already recorded, but it stops a 30-day delay from turning into 60 or 90 days, which is where real damage happens. If you can't clear the full amount, call the lender and ask what brings the account back to current.
2. Put every EMI and card on autopay
Your repayment record carries more weight than anything else in your CRIF score. Set up auto-debit for at least the minimum due on every card and the full EMI on every loan. People with good intentions still slip up because they forget, and one forgotten payment can stay visible in your DPD grid for years.
3. Get card usage under 30%
This is often the fastest win. If your total card limit is ₹1.5 lakh, aim to have your statement balance below ₹45,000. What gets reported is usually the balance on your statement date, not what you pay later. So paying a chunk before the statement is generated lowers your reported usage, even if you clear the full bill every month anyway.
4. Ask for a higher limit, if you trust yourself with it
A higher limit with the same spending means lower utilisation. Many issuers offer limit increases in their app. Ask your issuer whether the request involves a credit check, because some treat it as a hard enquiry. Skip this step completely if a bigger limit would tempt you to spend more.
5. Keep your oldest card open
An old account adds length to your credit history, and closing it can also raise your utilisation overnight. If the card has no annual fee, make a small purchase on it every few months and pay it off. If it does charge a fee, ask the issuer to waive it or move you to a no-fee version before you think about closing it.
6. Stop applying for new credit for a while
Every loan or card application adds a hard enquiry, and several in a short period make you look like you urgently need credit. If your score is under pressure, pause new applications for a few months. When you do apply, use the lender's eligibility check first, and apply only where you're likely to be approved.
7. Get errors on your report fixed
Mistakes are more common than most people expect: a closed loan still marked active, a late payment you never made, or someone else's loan attached to your PAN. Raise a dispute with CRIF High Mark or write to the lender with proof, such as a closure letter or bank statement. Under RBI rules, the complaint has to be resolved within 30 days, or you're owed ₹100 for each day of delay. Our CRIF dispute steps walk you through it.
8. Deal with settled and written-off accounts properly
A "settled" or "written-off" status tells lenders you didn't repay in full, and it weighs heavily on your score. If you can afford it, ask the lender what it would take to close the account in full, which usually means paying the amount that was waived. Get their agreement to update the status to "closed" in writing before you pay. Before settling any loan in the future, use our settlement impact calculator to see what it will cost your score, and read what written off means on your report.
9. Rebuild with a secured card if your history is thin or damaged
If lenders are turning you down, a credit card backed by a fixed deposit is one of the easiest approvals to get. Use it lightly and pay it in full every month. Six to twelve months of clean payments gives your CRIF report fresh, positive history to work with.
How long does it take for your CRIF score to improve?
Your score changes only when lenders report new data to CRIF High Mark. From 1 July 2026, lenders report four times a month, on the 9th, 16th, 23rd and the last day, and the bureau then takes a few days to process each update. Here's what that means for each fix:
If a month has passed and a change you made still isn't showing, the lender may not have reported it yet. Ask the lender to confirm what they sent, and raise a dispute if the record stays wrong.
What doesn't improve your CRIF score
- Paying someone to "delete" bad entries. Accurate information stays on your report, and nobody can legally remove it for a fee. Only errors can be corrected.
- Closing credit cards. It usually raises your utilisation and shortens your history, which is the opposite of what you want.
- Checking your score repeatedly. Checking your own score is a soft inquiry. It won't hurt you, and it won't help either.
- A salary hike. Your income isn't part of your credit report. It matters to lenders, but not to your score.
- Paying off a loan early to "boost" your score. Clearing debt is good for your finances, but closing a well-run loan early rarely lifts the score much, and it can reduce your credit mix.
A realistic 90-day plan
Month 1. Pull your CRIF report, clear anything overdue, set up autopay, and raise disputes for any errors.
Month 2. Bring each card's statement balance under 30% of its limit. Don't apply for any new credit. Check that your disputes are moving.
Month 3. Check your CRIF score again and compare it with month 1. If you're close to a band boundary, such as 730 or 750, keep utilisation low for one more reporting cycle before you apply for anything. It also helps to know which lenders check your CRIF score before you choose where to apply.
Not sure how much further you need to go? See what counts as a good CRIF score.
Frequently asked questions
Q.1 How can I increase my CRIF score fast?
The quickest changes usually come from lowering your credit card balances below 30% of the limit before your statement date, clearing any overdue amounts, and getting report errors corrected. These can show up within a few weeks, once your lenders report the change to CRIF High Mark.
Q.2 How long does it take to improve a CRIF score?
Small improvements often show within one to three months. Recovering from serious problems, like a written-off or settled loan, can take one to several years of on-time payments.
Q.3 Does paying off a loan increase my CRIF score?
Paying an overdue loan stops further damage and helps. Closing a loan that was already running well rarely raises the score much, and it can slightly reduce your credit mix.
Q.4 Can a settled status be removed from my CRIF report?
A settled status is accurate information, so it can't simply be deleted. Some lenders will update it to closed if you pay the amount that was waived. Get that agreement in writing before you pay.
Q.5 Does checking my CRIF score often lower it?
No. Checking your own CRIF score is a soft inquiry and has no effect on the score, however often you check.
Q.6 Check your CRIF score free
FixMyScore pulls your full CRIF High Mark report, shows which accounts are costing you points, and gives you a plan to fix them. Checking is a soft inquiry, so it never lowers your score. Check your CRIF report free, or get the app on Google Play or the App Store.
Sources: RBI Credit Information Reporting Directions, as amended (effective 1 July 2026); RBI framework on compensation for delayed updation or rectification of credit information (effective 26 April 2024). Timelines are typical ranges, not guarantees.